


Business growth is exciting. New ideas, expanded teams, bigger ambitions. All of it signals momentum. And for many businesses, that next phase requires capital before the returns arrive.
Before debt becomes the solution, however, many founders first explore different ways of funding growth, from revenue-based financing to more traditional lending routes. Understanding your options when it comes to finding small business funding can make the difference between taking on strategic investment and committing to financial obligations that limit flexibility later.
This is often where debt enters the picture. So-called “good debt” is borrowing with intention. It is used to fund assets or initiatives that are expected to generate long-term value. Think new equipment, improved infrastructure, market expansion, or operational upgrades. When used thoughtfully, this kind of debt can act as a growth accelerator rather than a financial burden.
What Actually Separates Good Debt From Bad Debt
The real distinction between productive and problematic debt is not the loan itself. It is the strategy behind it.
Debt supports growth when it is tied to a clear and realistic return. That return might come through increased revenue, improved efficiency, or lower operating costs over time. In these situations, the business is not simply taking on a liability. It is investing in its future ability to perform and repay.
Debt becomes riskier when it is reactive rather than strategic. Borrowing to cover recurring shortfalls, plugging cash flow gaps without a plan, or maintaining unsustainable operations tends to increase pressure rather than relieve it. This is often when businesses begin to feel constrained by repayments instead of supported by them.
Why Context and Timing Matter
Healthy borrowing decisions rarely happen in isolation. They sit alongside regular financial reviews, realistic forecasting, and a clear understanding of the business’s current position.
Seeking financial advice before committing to new debt can also surface risks that are easy to miss in periods of growth or urgency. This is especially important when expansion is happening quickly, and decisions feel time-sensitive.
New Section: Debt and Cash Flow Stability
Growth-related borrowing does not just affect long-term strategy. It can also reshape day-to-day financial stability.
Repayments, interest commitments, and revised operating margins can all influence how cash moves through the business, particularly during slower revenue periods or unexpected cost increases. This is why it is important to align borrowing decisions with your wider financing strategies for managing business cash flow, ensuring that short-term liquidity remains protected even while pursuing longer-term expansion.
Using Debt as a Tool, Not a Crutch
Used well, debt works in partnership with smart expansion. It allows businesses to move sooner, build capacity, and compete more effectively without overstretching internal resources.
Used poorly, it can quietly limit flexibility and decision-making long before the impact becomes obvious.
Understanding when debt is supporting your strategy, and when it is signalling a deeper issue, is what turns borrowing from a source of stress into a considered business tool. And for businesses already feeling weighed down by existing debt, stepping back to reassess its structure, purpose, and exit plan is often the most valuable first move.
As with any financial decision, borrowing should always be considered in the context of your wider business strategy and discussed with a qualified financial adviser.
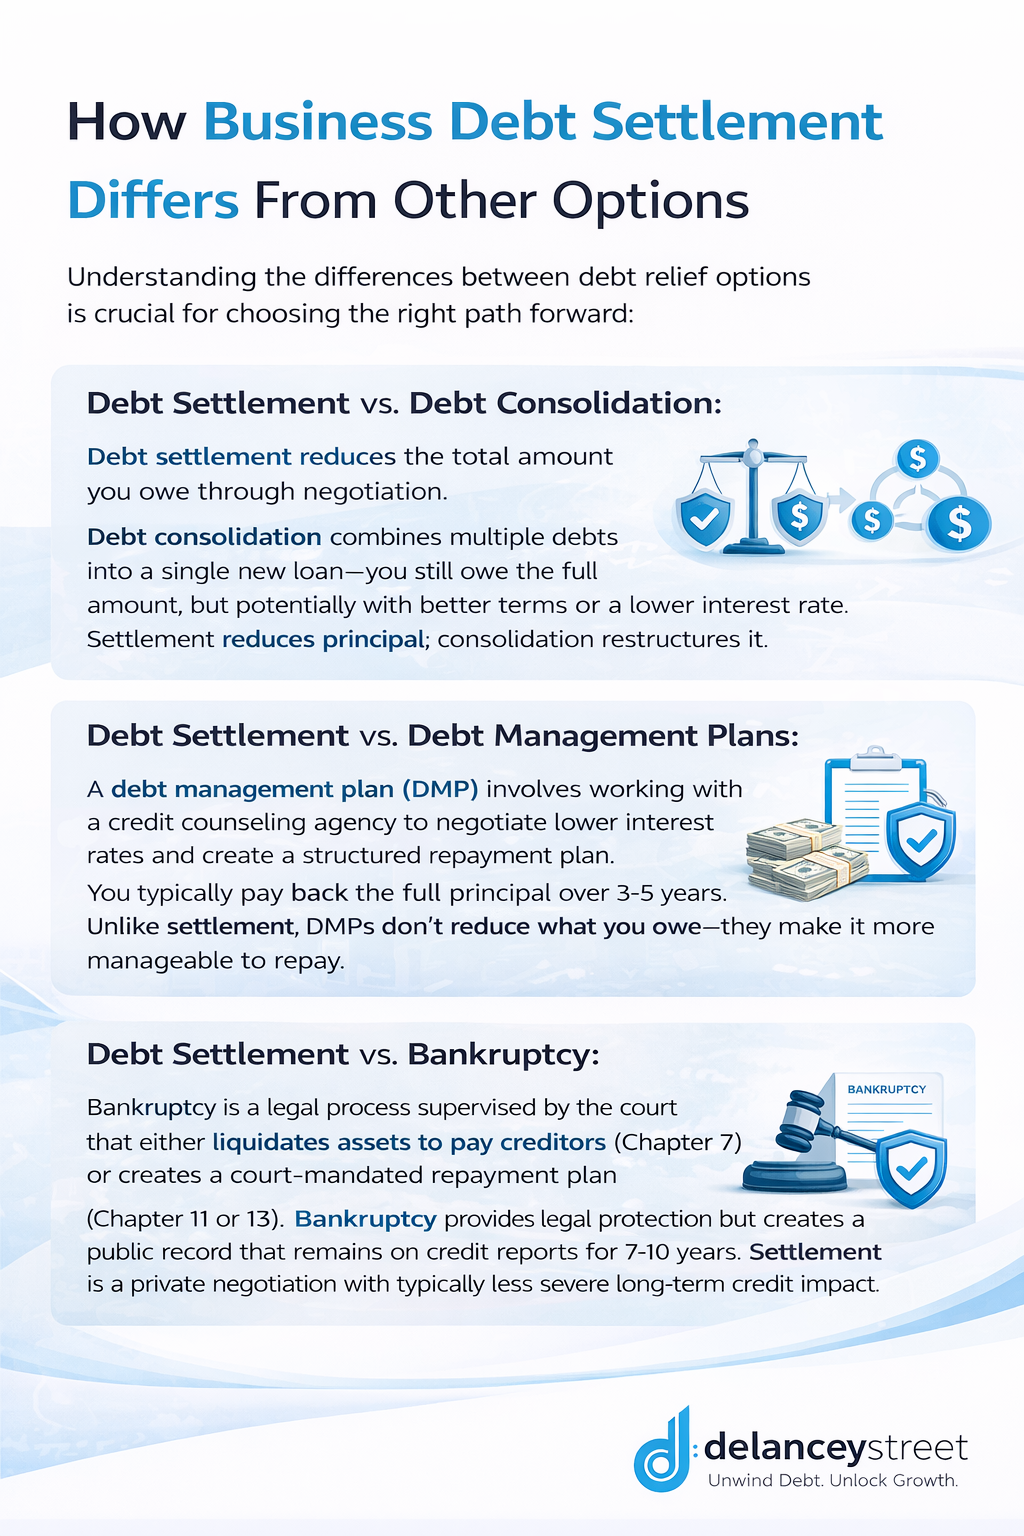
Infographic designed by Delancey Street
